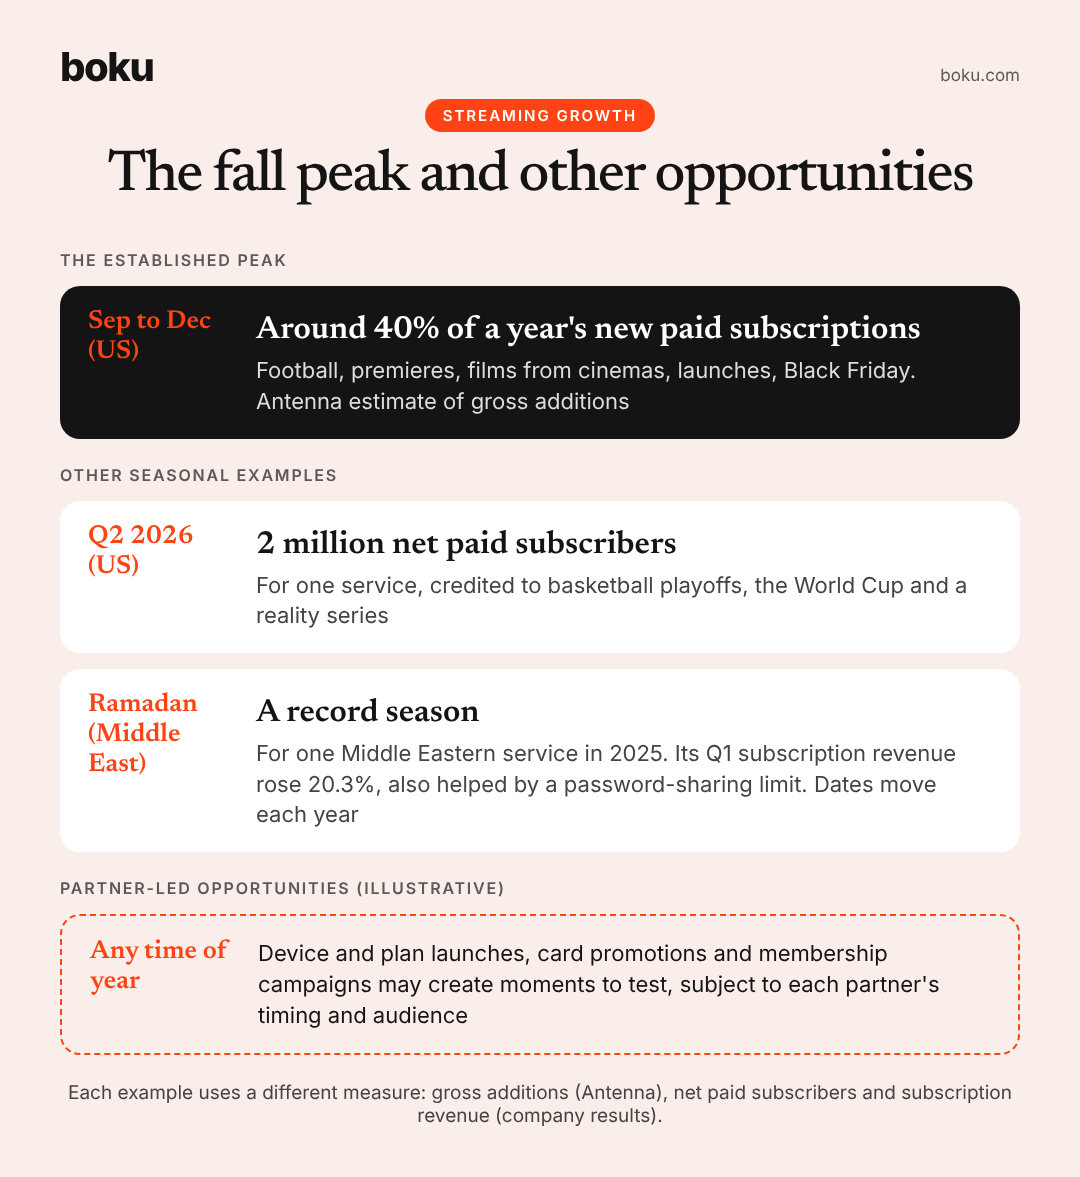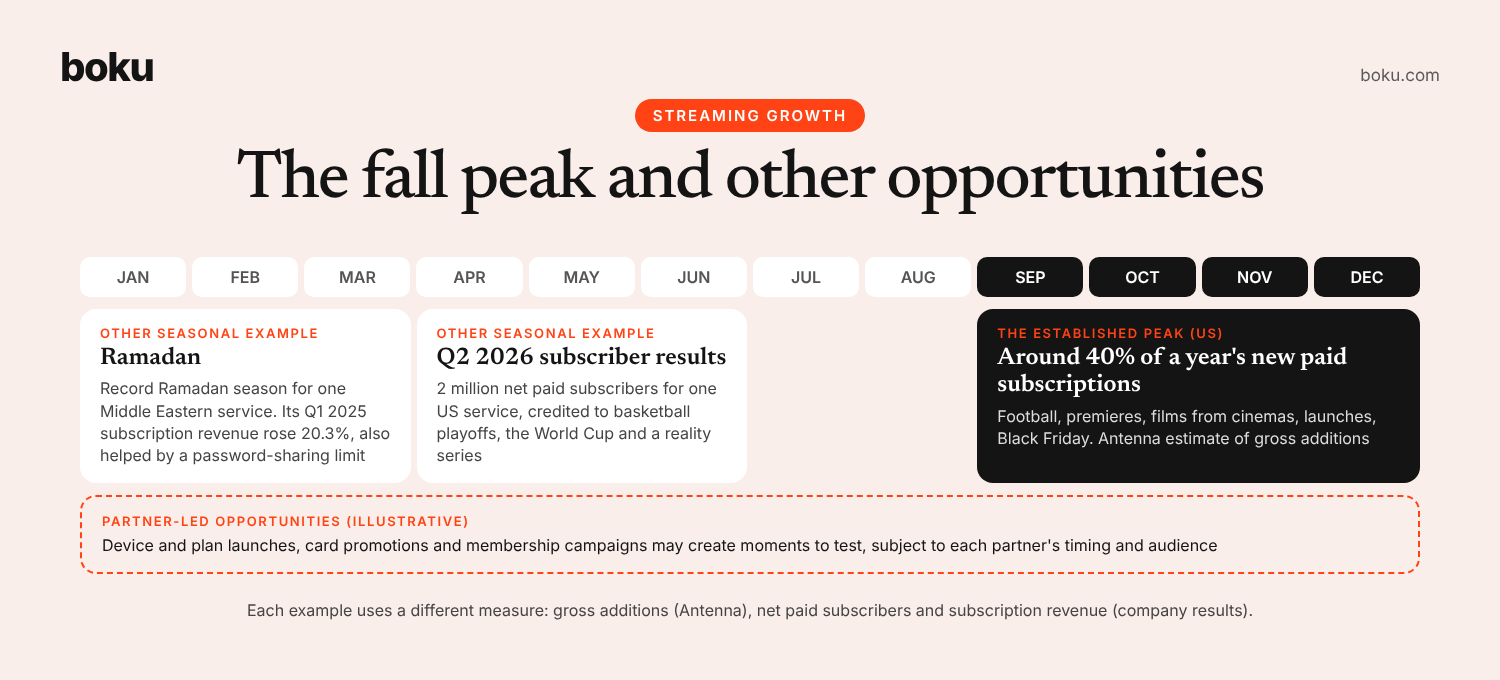
US streaming growth peaks in the fall because the main acquisition drivers land in the same months, such as football, premieres, films from cinemas, new launches and Black Friday. Antenna estimates around 40% of the US industry’s new paid subscriptions each year begin between September and December. Growth at other times can come from major events, other markets’ seasons and campaigns with distribution partners.
Fall has become US streaming’s biggest period for new subscribersA large share of US streaming’s subscriber acquisition now happens in the last four months of the year. Antenna estimates that around 40% of the industry’s new paid subscriptions each year begin between September and December. In 2025, 7 of the 8 premium subscription video services it tracks had their heaviest acquisition in those months.
A second Antenna measure points the same way. Net growth, which is new subscribers minus cancellations, was even more concentrated. Antenna’s 2025 review found that US premium services gained 31% of the year’s new paid subscriptions in the October to December quarter, and 57% of the year’s net growth. Those figures show when growth landed across the industry. How long the subscribers who joined in the fall go on to stay is a separate question that needs its own measurement.
Football, premieres, launches and Black Friday drive the US fall peakAntenna traces the pattern to US moments that now land in the same months. Football’s move to streaming brings surges in sign-ups, and shorter cinema windows bring more films to streaming in those months. Services schedule major premieres and returning series for September to December, and almost all new service launches of the past three years have come in the fall. Black Friday has become streaming’s most important promotional day. Distribution deals and promotions cluster in that period too, and more of the acquisition is on ad-supported plans. 52% of fall’s new paid subscriptions were on those plans in 2025, up from 43% in 2023. These are industry-level patterns. A service with a different audience or programming calendar may see a different peak, and services that do follow this one are competing for the same customers at the same time. A service’s own content and markets can bring customers in at other timesWith so much acquisition concentrated in the fall, streaming services have good reason to examine what could bring customers in during the rest of the year. Their own programming and markets are the first place to look. In the second quarter of 2026, one major US streaming service added 2 million net paid subscribers. Its parent company’s results credited basketball playoffs, the World Cup and a reality series with driving that growth. Outside the US, the calendar changes. In the first quarter of 2025, a major Middle Eastern streaming service had its strongest Ramadan season on record, its parent group’s results show. Subscription revenue rose 20.3% year on year, though the group also credited a new limit on password sharing with lifting subscriptions. The two examples measure different things: subscribers in one case and revenue in the other. Together they suggest that a service’s content, audience and local calendar can create demand outside the US fall, and because those moments are known in advance, they can be built into the acquisition plan. Partners can reach customers while they’re already selling something elseDistribution partners add opportunities a service can’t create on its own. A mobile network launching a new device or plan, a bank running a card promotion or a membership program planning a campaign is already in front of its customers. All can add streaming access to the offer being promoted. When the customer is already buying something, such as a new device or plan, the streaming offer can arrive as part of that purchase. That can put a subscription offer in front of people at a time when the service’s own calendar is quiet. But the fit has to be right. The partner’s customers need to be an audience the service wants, and the offer needs to give them a reason to sign up. Antenna found that distribution deals also cluster in the fall, which makes exploring partners with relevant campaigns planned between January and August a good move, provided their customers are a relevant match for the service. Boku’s bundling platform is built for running campaigns like these. A subscription business integrates once, then chooses its partners, markets and launch order, adding partners over time and tracking conversion, churn and subscriber growth for each one. Our guide to bundling for streaming services covers the terms to agree with a partner. Each campaign should be judged by the subscribers it keepsWhether a campaign runs in the fall, around a major event or with a partner, its sign-ups show how many people joined. The commercial test is how many stay, and whether the revenue they bring, directly or through a partner, covers what it cost to win and serve them. Comparing campaigns on those measures, by market and partner, shows which are worth repeating. Results can vary by market, partner and offer, so a well-designed test can help establish what made the difference in one setting, which may not carry over to another. Our guide to subscription bundle optimization covers how to set up those comparisons. Plan next year’s acquisition across the whole calendarFor US streaming services, the fall will remain an important acquisition period. Services looking for growth at other times of year can weigh opportunities from major sporting events and seasons in other markets to campaigns built with distribution partners. The decision is which opportunities justify investment, based on the subscribers they keep and the value they bring relative to their cost. FAQsWhen do streaming services get the most new subscribers? In the US, between September and December. Antenna estimates around 40% of the streaming industry’s new paid subscriptions each year begin in those four months, and in 2025, 7 of the 8 premium services it tracks had their heaviest acquisition then. Why do streaming sign-ups peak between September and December? Because the main US acquisition drivers share that period: football, premieres and returning series, summer films arriving from cinemas, new service launches and Black Friday promotions. Antenna also found that distribution deals and promotions cluster in the same months, so services compete for attention at the same time. How can streaming services grow outside the fall? By planning for other calendars: major events such as playoffs or the World Cup, seasons in other markets such as Ramadan, and campaigns with distribution partners. One major US service added 2 million net paid subscribers in the April to June quarter of 2026, growth its parent company credited to basketball playoffs, the World Cup and a reality series. How do distribution partnerships fit an annual acquisition plan? Partners such as mobile networks, banks and membership programs run their own campaigns through the year, such as device launches and card promotions. Adding a streaming offer to one of those campaigns can reach customers outside the fall, where the partner’s audience suits the service. Each campaign should then be judged on the subscribers it keeps and what they cost to win. What streaming industry trends shape subscriber growth? In the US, two stand out. One is the concentration of acquisition in the fall, when Antenna estimates around 40% of a year’s new paid subscriptions begin. Another is the shift to ad-supported plans: 52% of fall’s new paid subscriptions were on those plans in 2025, up from 43% in 2023. Key takeaways
|